Most Michigan slip-and-fall claims resolve for modest amounts, not the very large sums you sometimes see advertised. There is no reliable statewide average, but liability strength, injury severity, medical costs, lost income, and the property owner’s insurance limits drive every outcome. Catastrophic cases with permanent injury and clear negligence can reach six figures or more. If you’re hurt, the clock is already running: preserve evidence now and get a legal review before the 120-day notice window or the three-year deadline closes.
TL;DR:
- Settlement amounts depend heavily on injury severity and insurance limits; minor soft-tissue cases often settle for $5,000 to $25,000, while fractures and catastrophic injuries can reach six figures or more.
- Liability hinges on whether the property owner had actual or constructive notice of the hazard, with evidence like inspection logs, prior complaints, and surveillance footage playing a key role.
- The three-year Michigan statute of limitations generally allows time to file, but claims on public property require notice within 120 days, making early legal review crucial.
- Recent legal shifts, especially the Kandil-Elsayed decision, mean hazards are no longer automatically a complete defense if they were visible, shifting focus to reasonableness and fault distribution.
- Gathering evidence quickly, like photos, witness info, and medical records, significantly influences case value, and involving a lawyer is recommended if liability is disputed or damages are substantial.
Table of Contents
- What Slip and Fall Settlements in Michigan Typically Look Like
- Key Factors That Control Settlement Value in Michigan
- Timing and Deadlines: Statute of Limitations and Government Notice Rules
- Proving Liability and Defeating Common Defenses After Kandil-Elsayed
- Evidence Checklist: What to Do at the Scene and the First Week After a Fall
- Should You Hire a Lawyer? Contingency Fees and Free Consults Explained
- How Settlements Are Calculated and What Reduces Your Net Recovery
- Typical Steps and Strategies During Settlement Negotiations
- Compensation Beyond Medical Bills and Lost Wages
- What Happens If a Settlement Offer Is Rejected or Talks Stall
- How to Initiate a Slip and Fall Claim in Michigan
- An Attorney’s Perspective: What Actually Changes the Outcome
- Get a Free Case Evaluation From Keller & Keller
- Sources
- FAQ
What Slip and Fall Settlements in Michigan Typically Look Like
Search “average slip and fall settlement Michigan” and you’ll find dozens of numbers claiming to be the answer. Almost none of them are. Michigan courts do not publish a running tally of slip-and-fall settlements, and the figures law firms post online are usually cherry-picked wins, not statistical averages. A firm showcasing a $500,000 result isn’t lying, but it also isn’t telling you what happens to the other nine cases that settled for $15,000 or got denied outright.
The honest answer is that value swings wildly based on the facts of your fall. Here’s roughly how three common scenarios tend to shake out:
- Minor soft-tissue injury (sprained ankle, bruised hip, short recovery): often in the $5,000 to $25,000 range, largely driven by medical bills and a few weeks of missed work.
- Fracture requiring surgery (broken wrist, hip fracture, torn ligament needing repair): commonly $50,000 to $150,000, depending on hardware, physical therapy duration, and whether the injury causes lasting limitation.
- Catastrophic or permanent disability (traumatic brain injury, spinal cord damage, permanent mobility loss): can exceed $250,000 and occasionally reach seven figures, but only when liability is strong and the defendant carries enough insurance to pay it.
That last qualifier matters more than most injured people realize. A grocery store or apartment complex typically carries a commercial general liability policy with a set limit, often $1 million, sometimes far less for smaller property owners. If your damages genuinely total $2 million but the policy caps out at $500,000, that cap becomes the practical ceiling on what you can collect from that defendant, absent other insurance or assets to pursue.
Pro Tip: Ask early whether the property is owned by the business operating there or by a separate landlord entity. Sometimes there are two policies in play, which can meaningfully raise the total available coverage.
There’s no reliable statewide average for a slip and fall settlement in Michigan, and any calculator promising one is guessing. What actually moves the needle is covered next.
Key Factors That Control Settlement Value in Michigan
Insurance adjusters evaluate every slip-and-fall claim against the same checklist, whether they say so or not. Understanding that checklist tells you exactly where to focus your energy.
Liability strength comes first. Michigan premises liability turns on whether the property owner had actual or constructive notice of the hazard, meaning they knew about it or reasonably should have discovered it through routine inspection. Evidence that helps here includes maintenance and inspection logs, prior customer complaints about the same spot, surveillance footage showing how long a spill or ice patch sat there, and statements from employees or other witnesses who saw the condition develop.
Injury severity and documentation come next. Adjusters weigh the seriousness and permanence of the injury, the consistency of your medical treatment, and whether a treating physician or specialist has offered an opinion on future care needs. Gaps in treatment or skipped appointments give insurers an easy argument that you weren’t really hurt.
Economic losses get calculated with precision:
- Medical bills, past and projected
- Lost wages during recovery
- Diminished future earning capacity if the injury limits your work long-term
Noneconomic losses are harder to pin down but still count. Pain, suffering, and loss of enjoyment of normal activities don’t come with a receipt, so adjusters lean on medical records, personal statements, and sometimes testimony from family members to gauge severity. Michigan juries tend to award more generously here than insurance adjusters initially offer, which is part of why cases with strong documentation often settle higher once litigation becomes a real threat.
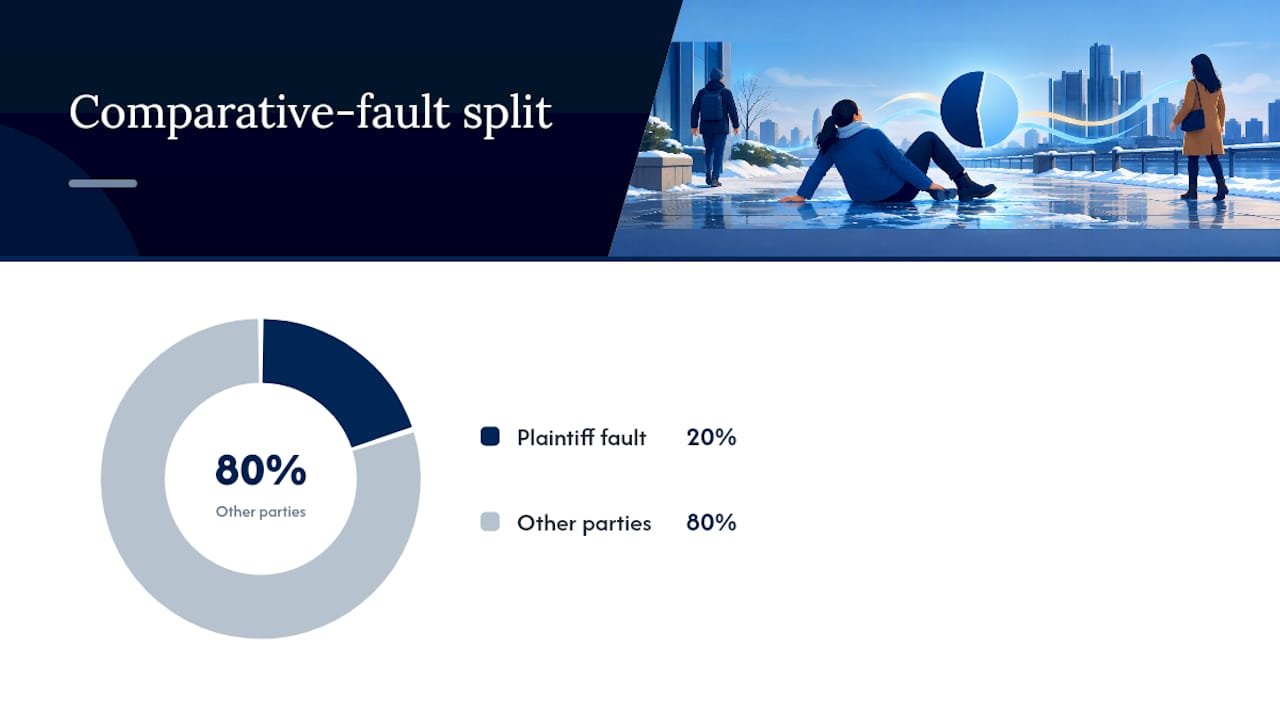
Comparative fault reshapes the math. Under Michigan’s comparative-fault statute, your damages get reduced by your percentage of fault rather than eliminated outright. If a jury finds you 20% responsible for not watching where you stepped, a $100,000 award becomes $80,000. If your fault exceeds the combined fault of everyone else, Michigan law can also block noneconomic damages entirely, so fighting over that percentage is not a minor detail.
Timing and Deadlines: Statute of Limitations and Government Notice Rules
Michigan gives most injury victims three years from the date of the fall to file a lawsuit, under MCL 600.5805. Missing the statute of limitations typically means your claim will not proceed, no matter the strength of your evidence.
But three years is the wrong number to remember if your fall happened on a public sidewalk, road shoulder, or other government-owned property. Those claims carry a separate and much shorter clock:
- File a written notice within 120 days of the fall under MCL 691.1404, addressed to the specific governmental entity responsible for the property, which could be a city, county, or the Michigan Department of Transportation.
- Describe the location and defect with precision. Michigan courts have upheld dismissals where a notice was vague about exactly where the hazard sat or what caused it.
- Confirm the correct defendant early, since sidewalks can belong to a city while an adjacent road shoulder belongs to the county or state, and notifying the wrong entity doesn’t stop the clock on the right one.
Michigan Court of Appeals decisions have repeatedly enforced this strictly. In one case involving the City of Detroit, the court found that a notice lacking sufficient precision about the defect’s location failed to satisfy the statute, effectively ending that claim before it started. A 120-day deadline sounds generous until you realize most people don’t even know it exists until it’s already passed.
The practical lesson is simple: if your fall happened anywhere near a public sidewalk, parking structure, or road, treat the first days after your injury as urgent, not just physically but legally.
Proving Liability and Defeating Common Defenses After Kandil-Elsayed
For years, Michigan defendants used the “open and obvious” doctrine like a trapdoor. If a hazard was visible enough that a reasonable person should have noticed it, the property owner often escaped liability entirely, no matter how negligent their upkeep had been.
That changed with the Michigan Supreme Court’s Kandil-Elsayed decision. The court held that whether a hazard was open and obvious now factors into breach of duty and comparative fault, rather than automatically wiping out the property owner’s duty to keep the premises safe. In practice, that means a visible hazard no longer guarantees a defense win. It becomes one factor in how fault gets divided between you and the property owner.
The shift matters because it moves the fight from “was this hazard visible” to “did the property owner act reasonably given that visibility, and how much of the fault belongs to each side.” That’s a fundamentally different argument, and it’s one plaintiffs can actually win with the right evidence.
Constructive notice remains a central battleground too. Insurers will argue the hazard appeared too recently for the property owner to have reasonably discovered it. You rebut that with evidence showing how long the condition existed and how routine inspections should have caught it:
- Inspection and maintenance logs showing gaps in routine checks
- Surveillance footage timestamping when the hazard first appeared
- Prior complaints from other customers or tenants about the same or similar conditions
- Employee schedules showing how long the area went unchecked
Expect defendants to raise three defenses in nearly every case: the hazard was open and obvious, they had no notice of it, or you were careless. Recent legislative fights over rolling back Kandil-Elsayed’s protections show just how much insurers want that old trapdoor back, which tells you everything about how much it actually helped injured people.
Evidence Checklist: What to Do at the Scene and the First Week After a Fall
What you do in the first 24 to 48 hours after a fall often determines whether your claim is worth pursuing at all. Surveillance footage gets overwritten. Hazards get repaired. Memories fade.
- Photograph everything at the scene, both wide shots showing the full area and close-ups of the specific hazard, ideally with something for scale.
- Take video if possible, since it captures lighting, foot traffic, and context that still photos miss.
- Preserve the shoes and clothing you were wearing. Don’t wash them; insurers sometimes argue about tread or footwear as a defense.
- Get names and contact information from any witnesses before they leave. People rarely come back on their own.
- Request or complete an incident report with the property manager or business on-site, and ask for a copy before you leave.
- See a doctor promptly, even if you think the injury is minor, since delayed treatment is one of the easiest excuses insurers use to minimize a claim.
- Keep every medical bill, receipt, and record, along with a simple log of missed workdays and daily activities you couldn’t perform.
Pro Tip: Send a written request asking the property owner to preserve surveillance footage and maintenance records within the first few days. Many businesses overwrite security footage automatically after just a week or two, and a written preservation request creates a paper trail if they don’t comply.
Should You Hire a Lawyer? Contingency Fees and Free Consults Explained
Not every fall needs a lawyer. If liability is undisputed, your injury was minor, and the insurer’s first offer covers your bills and lost time fairly, handling it yourself is reasonable. But several situations tip the scale toward getting representation:
- The property owner or their insurer disputes that they were at fault
- Medical bills are significant or ongoing care is likely
- Health insurance or Medicare liens complicate how much you’ll actually net
- The first offer feels low relative to your bills and lost income
Michigan personal injury attorneys, including Keller & Keller, typically work on contingency, meaning you pay nothing upfront and no fee at all unless the case settles or wins. Case-related expenses are usually advanced by the firm and repaid out of any recovery. A free consultation generally covers reviewing incident reports, medical records, photos, and witness information to give you an honest read on whether representation would help.
What a lawyer actually adds is investigation muscle you can’t easily replicate alone: formal record requests, expert opinions on future care, lien negotiation with insurers, and settlement leverage that comes from being ready to file suit if the offer doesn’t reflect the real value of your case.
How Settlements Are Calculated and What Reduces Your Net Recovery
A settlement headline and the check you actually deposit are rarely the same number. Settlements combine economic damages (medical bills, lost wages, future care costs when injuries are permanent) with noneconomic damages (pain, suffering, loss of enjoyment of life). Both get added together, then reduced by whatever offsets apply to your specific case.
Common deductions include:
- Medical liens from hospitals or health providers that treated you on the promise of repayment from your settlement
- Medicare or Medicaid subrogation claims, which can legally require repayment out of your recovery if those programs paid for your care
- Attorney fees, typically a percentage of the gross settlement under a contingency agreement
- Case expenses, like fees for medical record retrieval or expert reports, usually repaid from the settlement itself
Michigan’s no-fault insurance system can also intersect with a premises claim if your health coverage or auto policy already paid some medical bills, which affects how liens get resolved. A $100,000 settlement can easily net $50,000 to $65,000 after fees and liens, which is why understanding these deductions upfront matters more than fixating on the gross number.
Typical Steps and Strategies During Settlement Negotiations
Negotiations rarely move in a straight line. The process typically starts with a demand letter laying out liability, medical treatment, and a specific dollar figure, sent once your treatment has stabilized enough to estimate total damages accurately. Sending a demand too early, before you know the full scope of your medical needs, tends to undervalue the claim.
The insurer’s first response is almost always lower than the demand, sometimes dramatically so. This isn’t necessarily bad faith; it’s a standard opening move meant to test how firm your evidence is. What follows is usually a back-and-forth of counteroffers, each side adjusting based on new information, whether that’s additional medical records, a physical therapy update, or wage documentation.
Strong negotiating leverage comes from being genuinely prepared to file a lawsuit if the offer doesn’t improve. Insurers price in litigation risk. A claimant who has clearly done the work, organized medical records, documented lost income, and secured witness statements, tends to get better offers than one who appears unprepared to escalate.
Timing matters too. Settling before you’ve reached maximum medical improvement, the point where your treating doctor says your condition has stabilized, risks accepting a number that doesn’t account for lingering or worsening symptoms. Patience during negotiations usually pays off financially, even though it’s emotionally difficult when you’re dealing with bills and lost income in the meantime.
Compensation Beyond Medical Bills and Lost Wages
Medical expenses and lost income are the easiest damages to calculate, but they’re rarely the whole story. Michigan slip-and-fall settlements can include several other categories of compensation depending on your specific circumstances.
Pain and suffering covers the physical discomfort and disruption to daily life caused by the injury, separate from any dollar amount tied to treatment. Emotional distress compensation addresses anxiety, sleep disruption, or psychological impact that sometimes follows a serious fall, particularly when the injury causes lasting disfigurement or disability.
Loss of consortium claims, though less common, allow a spouse to seek compensation when the injury disrupts the marital relationship. Property damage gets included when personal items were damaged in the fall itself, a broken phone, torn clothing, a shattered watch. Loss of earning capacity differs from lost wages in that it accounts for permanently reduced future income potential, not just time missed during recovery.
Each of these categories requires its own documentation. A pain journal, statements from family members about behavioral changes, or a vocational expert’s assessment of reduced earning potential all strengthen these claims. Skipping this documentation is one of the most common reasons injured claimants leave real money on the table.
What Happens If a Settlement Offer Is Rejected or Talks Stall
When negotiations stall, you have options beyond simply accepting a low offer out of frustration. The most common next step is formally rejecting the offer in writing with a counteroffer that restates your evidence and reasoning, sometimes accompanied by additional medical documentation the insurer hasn’t yet seen.
If the insurer still won’t move to a fair number, filing a lawsuit becomes the practical leverage point. Filing doesn’t mean you’re guaranteed to go to trial. Most Michigan personal injury lawsuits still settle before trial, often during mediation or shortly after depositions reveal how strong the evidence actually is. But filing signals seriousness and starts the discovery process, where both sides exchange evidence and can no longer avoid difficult facts.
Mediation is a common middle step, where a neutral third party helps both sides find common ground without the cost and unpredictability of a trial. If mediation fails and the case does go to trial, a jury decides both liability and damages, which introduces more uncertainty but also removes the insurer’s ability to simply lowball you indefinitely.
The decision to litigate rather than settle for less isn’t just legal strategy, it’s a calculation about how much your case is genuinely worth versus how much time and uncertainty a trial adds. This is precisely the kind of decision where experienced legal counsel earns its contingency fee.
How to Initiate a Slip and Fall Claim in Michigan
Starting a Michigan slip and fall claim follows a fairly consistent sequence, though the details shift depending on whether the property is privately owned or government-controlled.
First, identify every potentially responsible party. That might be a store owner, a landlord, a property management company, or a municipality if the fall happened on a public sidewalk. Getting this wrong early, especially for government claims, can cost you the case entirely given the 120-day notice deadline discussed earlier.
Second, notify the responsible party or their insurer that you intend to pursue a claim. For private property owners, this often happens naturally through the incident report process. For government entities, this step is the formal written notice required under MCL 691.1404, and it needs to happen fast.
Third, gather and organize your evidence, photos, medical records, witness statements, and the incident report, into a coherent file that supports both liability and damages. Fourth, consult with a personal injury attorney, ideally before your medical treatment concludes, so they can guide record requests and evidence preservation while things are still recoverable. Finally, once your treatment has stabilized enough to know your total damages, your attorney sends a demand letter to the insurer, opening formal negotiations.

Skipping steps or moving too slowly through this sequence is the most common reason otherwise strong claims lose value.
An Attorney’s Perspective: What Actually Changes the Outcome
Most people search for a settlement number when they should be asking a different question: what evidence exists to prove this wasn’t just an accident? Realistic expectations matter, but they matter less than what you do in the first week. A well-documented fall with weak damages often outperforms a serious injury with no photos, no witness names, and a repaired hazard.
The 120-day notice deadline catches more good claims than bad legal arguments ever do. If your fall involves any public property, get a legal review immediately, not eventually. Keller & Keller has built its Michigan premises liability practice around exactly this kind of urgency, because the difference between a fair settlement and a barred claim is often measured in days, not months.
— Adam
Get a Free Case Evaluation From Keller & Keller
Reading about Michigan premises liability law helps you understand your situation, but it doesn’t replace a real evaluation of your specific fall. Some firms offer a free case evaluation for Michigan slip-and-fall claims, often with contingency fee arrangements where you owe nothing unless they win or settle your claim.
Bring what you have when you reach out, even if it feels incomplete: photos from the scene, any medical records or bills so far, a copy of the incident report if one exists, and contact information for witnesses. If your fall happened near a sidewalk, parking lot, or other government property, mention that immediately given how tight the 120-day notice window is. A short conversation now can be the difference between a claim that moves forward and one that quietly runs out of time. Start your free evaluation today at 2keller.
Sources
- MCL – Section 600.2958 – Michigan Legislature
- KANDIL-ELSAYED v F & E OIL, INC (Michigan Supreme Court opinion)
- COA opinion (Dentamaro Seguna v City of Detroit)
This article is general information, not a substitute for advice from a qualified lawyer. Consult a qualified legal professional about your own circumstances before acting on anything here.
FAQ
What Is the Average Settlement for a Slip and Fall in Michigan?
There’s no reliable statewide average, since outcomes depend heavily on liability strength, injury severity, and insurance limits. Minor injuries often settle in the $5,000 to $25,000 range, while fractures requiring surgery commonly land between $50,000 and $150,000, and catastrophic injuries can exceed $250,000 when liability is clear.
What Counts as a Good Settlement Offer for a Slip and Fall?
A good offer fully covers your medical bills, lost income, and future care needs, plus fair compensation for pain and suffering, without requiring you to absorb costs the property owner should be responsible for. If an offer barely covers your medical bills with nothing left for lost wages or pain, it’s usually worth negotiating further or consulting an attorney before accepting.
How Long Does It Take to Settle a Slip and Fall Case in Michigan?
Straightforward cases with clear liability and completed medical treatment can settle within a few months of a demand letter. Cases involving disputed liability, serious injuries, or litigation often take a year or more, particularly if the claim proceeds to filing a lawsuit and discovery under Michigan’s three-year statute of limitations.
What Is the Typical Payout for a Slip and Fall?
Typical payouts vary widely because they depend on the specific injury, liability evidence, and applicable insurance policy limits rather than a fixed formula. Most claims resolve in the low-to-mid five-figure range, while catastrophic injury cases with strong liability evidence can reach six figures or more.
Do I Need a Lawyer for a Michigan Slip and Fall Claim?
You don’t always need one for minor, undisputed claims, but representation typically helps when liability is contested, medical bills are significant, or the property involved government-owned sidewalks with strict notice deadlines. Firms like Keller & Keller offer free case evaluations and work on contingency, so there’s no upfront cost to find out where you stand.